2026 China Tea Report: Production and Exports
For the global tea industry, 2025 was another year of expansion both in production volumes and in exports out of tea-producing countries. China remained at the center of that story, adding to its acreage and output while further consolidating its standing as the world’s leading tea producer. China’s
western provinces continued to anchor the country’s dominance, and green tea’s share of production grew yet again. China’s tea trade either maintained its dominance or gained further ground in its African and West Asian markets, and domestic consumption expanded as well.
Tea Production in 2025
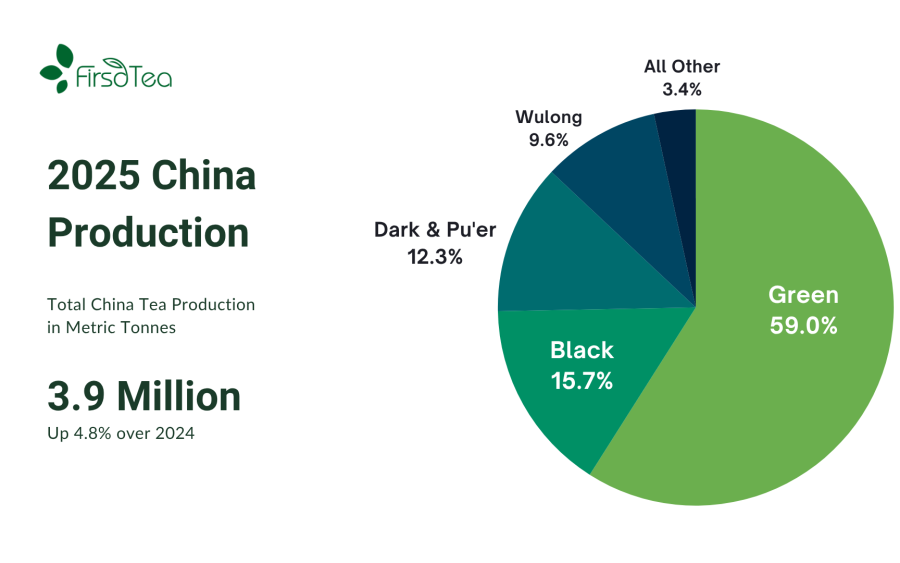
Total global tea production reached 7.27 million metric tons (mmt) in 2025, a 2.5 percent increase over 2024’s 7.09 mmt. China’s output of 3.92 mmt, up 4.8 percent year-over-year, accounted for 53.9 percent of that global total, reinforcing its long-held position as the world’s largest producer. India ranked second at 1.37 mmt (18.9 percent), and Kenya placed third with 549,000 metric tons (7.6 percent). These three countries together supplied more than 80 percent of global tea production for the year.
Green tea’s share of China’s production continued to climb, reaching 59.0 percent of output, or 2.15 mmt. Black tea followed at 15.7 percent, or 569,700 metric tons (mt), sustaining its multi-year trend of gaining ground within China’s production mix. The domestic market has been a driver of black tea’s rise: bubble teas and other “new-style tea beverages” have brought black tea into broader everyday consumption, and that trend shows no sign of slowing. China’s green tea output on its own remains a defining feature of global tea supply.
At the provincial level, Fujian reclaimed the top production ranking with an estimated 550,000 mt, nearly 10 percent above 2024 levels. Yunnan placed second at approximately 430,000 mt, with Sichuan close behind in third. Hubei and Guizhou both exceeded 400,000 mt, rounding out the top five. The Western Belt (Yunnan, Sichuan, and Guizhou) remains the country’s
dominant producing region, while the Eastern Belt (Fujian, Anhui, and Zhejiang) and Central Belt (Hubei, Hunan, and Shaanxi) each continue to contribute substantial volumes.
China’s total tea acreage reached 3.54 million hectares (ha), extending a multi-year upward trend. Yunnan holds the most hectares of any province at over 533,000 ha, followed by Guizhou at over 466,000 ha, Sichuan at more than
383,000 ha, and Hubei close behind in fourth. Beyond acreage growth, a range of quality and efficiency initiatives are actively reshaping how tea is grown and processed across the country. These include the deployment of advanced harvesting machinery, improved farm layouts, the introduction of higher-yielding tea varieties, and in some areas, the use of drones to transport raw leaf to processing facilities. Provinces like Guizhou and Anhui are extending their
productive windows by adding harvest seasons, while China is also developing its own domestic maximum residue level (MRL) standards — a signal of the country’s intent to raise the bar on quality for both export and home markets.
China’s Tea Exports
China’s tea exports grew 12 percent in 2025 to 418,800 mt, maintaining its position as the second-largest exporting country. Global exports from producing countries reached 2.01 mmt, up 2.1 percent over 2024. Kenya led all exporters with 580,000 mt (28.9 percent of the global total), though its share edged downward from recent highs. India came in third with 280,400 mt, itself up 13 percent year-over-year. At 10.7 percent of annual production, China’s export-to-production ratio remained consistent with prior years.
Green tea accounted for 88.1 percent of China’s export volume at 369,100 mt, up 14 percent over 2024. Black tea represented 6.2 percent of exports
at 26,200 mt. The average export price across all tea types was USD $3.69 per kg. Morocco held its place as China’s top export market, importing 91,575 mt, up 13.6 percent and accounting for roughly 21.8 percent of China’s total tea exports, in line with its average historical 20 percent share. Uzbekistan climbed to second with 29,601 mt, an 18.8 percent gain, while Senegal reached third place with 23,981 mt. This represented a 58.3 percent increase
over 2024, a notable destination-level story that highlights a rising trend in demand across several African countries.
Looking Forward
China continues its forward momentum in tea, with an expansion of production area, stronger crop management, and the adoption of improved technologies. Domestic demand continues to see growth from bottle teas and the expansion of teabased retail beverage chains. Additionally, global demand for matcha will drive a short-term boost in Chinese tea exports, while potentially creating
challenges to steady supply of steamed green teas. Overall, these conditions reflect growing pains for an expanding industry.
- Jason Walker is marketing director of Firsd Tea North America. Prior to his work with Firsd Tea, Walker served in a variety of roles in tea and beverage business capacities. His experience includes business services for small tea companies, a top-ranked online destination for tea consumer education and co-founding a coffee business. His insights draw upon his diverse range of experience in sales, operations and management in the tea world.
He may be reached at: [email protected].